How to Qualify for a Home Equity Loan in 2026
The RefiGuide provides an depth look at what homeowners need to qualify for a home equity loan in 2026. Our team lays out the home equity loan requirements and guidelines for the most popular 2nd-mortgage programs today. Home equity loans continue to serve as vital tools for homeowners seeking to unlock their property’s value. With… Read More »
HELOC vs Home Equity Loan

In 2026, borrowers continue to choose a HELOC or home equity loan to pull out cash from the equity in their property, because they want to keep their low first mortgage interest rate. Before taking out a second mortgage against your property, you need to understand the benefits and risks of home equity loans and… Read More »

How to Use Home Equity to Build Wealth

In 2026, with the U.S. median home price at approximately $425,000 and American homeowners collectively holding an estimated $34 trillion in tappable home equity (Federal Reserve, 2026), that equity represents one of the most powerful — and underutilized — wealth-building tools available to the average household. Home equity is simply the difference between your home’s… Read More »

How Does a Second Mortgage for Home Improvement Work?

A second mortgage for home improvement and remodeling works by allowing you to borrow against the equity you have already built in your home without touching your existing first mortgage and receive a lump sum or revolving credit line that funds your renovation project at a significantly lower interest rate than credit cards or personal… Read More »

What Are the Rates for a Home Equity Loan Today?

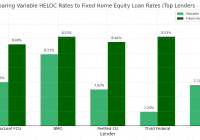
The national average fixed home equity loan rate is 7.42% as of late September 2026, according to Curinos. For a HELOC, the Bankrate national average sits at 7.28%. Now the more useful question: why won’t you get that rate? National averages are built on a specific borrower — typically a $30,000 loan at 700 FICO… Read More »

How to Apply for a 2nd Mortgage

Applying for a second mortgage in 2026 has become increasingly accessible thanks to digital application platforms, competitive lender rates, and record levels of home equity held by American homeowners. Whether you’re looking to consolidate debt, fund home improvements, or finance a major purchase, understanding the second mortgage application process can save you time, money, and… Read More »

What Can You Use a HELOC for​?

You can use a HELOC for virtually any purpose: home renovations, debt consolidation, education, medical bills, real estate investment, business funding, or emergency reserves, but not all uses are created equal financially, and one specific use unlocks a tax deduction that the others do not. As a home equity lending expert with nearly 30 years… Read More »

Investment Property Equity Line of Credit Advantages

For real estate investors seeking flexible, powerful financing solutions in 2026, few tools match the strategic versatility of a Home Equity Line of Credit (HELOC) on investment property. While taking out an equity line of credit on a rental or non-owner occupied property comes with stricter HELOC requirements than financing your primary home. the advantages… Read More »

Can You Pay Off a HELOC During the Draw Period?

Yes, you are allowed to pay off a HELOC during the draw period, and doing so is one of the smartest financial moves available to homeowners carrying HELOC debt at today’s rates. However, there is one critical distinction that trips up thousands of borrowers every year: paying down your balance to zero is not the… Read More »

No Appraisal Home Equity Loan

As a home equity lending expert who has guided thousands of American homeowners through the equity borrowing process over the past 15 years, I’ve witnessed a transformative shift in how lenders evaluate properties for home equity loans. The emergence of no-appraisal home equity loans represents one of the most significant innovations in our industry, fundamentally… Read More »